Operation Blackjack: The Story of Terrorist Nuclear Attacks on Major Western Cities
January 13th, 2009Update 1/20/2009
I think that this is some sort of viral marketing stunt. I can’t really imagine what the product might be. At best, there can’t be more than a couple of thousand people paying attention to it.
If you’re interested in following this, whatever it is, the thread to watch is here.
—END UPDATE—
This little curiosity comes to us from the Telegraph’s Culture Picture Galleries section.
As of now, there’s an entry called: Operation Blackjack: The Story of Terrorist Nuclear Attacks on Major Western Cities.
On the page, we read: Blackjack – A slide show story. The events portrayed in this slide show are entirely fictitious.
There is no author listed.
I didn’t spend too much time gazing at the chicken entrails, but there were a few howlers that were too good to pass up:
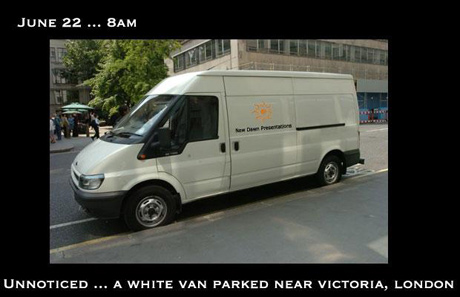
Remember the Kingstar (controlled demolition company) van near the exploded bus on the 7/7 London bomings? That’s what came to mind for me.
Also, the ‘fictitious’ attack occurs during the Summer solstice. What’s the name on the side of the van? New Dawn Presentations. And its logo? That’s right, the Sun.
One other thing: All the cool kids know that the Illuminati are fascinated with Ferris wheels near bodies of water. (Look, don’t blame me, I just work here.)
Take a look at this frame from our little slide show narrative:
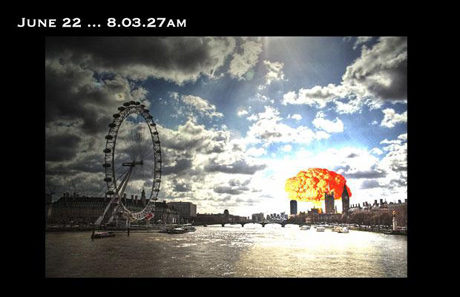
Coincidences and mushroom clouds…
Have a nice day!
Research Credit: TD
NEW ZEALAND’S CREDIT RATING MAY BE CUT
January 13th, 2009Privately, with friends and family, I’ve been referring to New Zealand as Iceland 2. The financial situation here is not quite as absurd as Iceland’s, but the comparison is legitimate because of New Zealand’s extremely high debt load.
If Germany is having trouble with its bond auctions, how is New Zealand going to manage?
With great difficulty, at best.
Via: Bloomberg:
New Zealand’s AA+ foreign-currency credit rating may be cut if the nation’s current account deficit and overseas debt begin to curb growth and investment, Standard & Poor’s said.
The rating company affirmed the rating, though revised the outlook to negative from stable, according to a statement today. The AAA local-currency rating is affirmed with a stable outlook.
New Zealand’s dollar fell to a four-week low after the statement, which adds to signs that investors may turn away from an economy that is in a prolonged recession. A report earlier today showed business confidence has slumped to a 34-year low and the government last month forecast widening budget deficits over the next five years.
“It’s not going to be easy for New Zealand,” said Adam Carr, a senior economist at ICAP Australia Ltd. in Sydney. “They have a massive current account deficit and a sizeable budget deficit. These are two things that aren’t good to have in an environment when it’s a struggle to raise capital.”
New Zealand’s dollar fell to 56.45 U.S. cents at 2:40 p.m. in Wellington from 57.17 cents immediately before the S&P report and from 57.93 cents in late Asian trading yesterday.
GERMAN BOND AUCTION FAILS
January 13th, 2009I haven’t gotten around to writing my 2009-year-ahead post. In the interim, here’s what I wrote to a core Cryptogon supporter a few days ago:
The phase we’re into now is akin to a car on an icy road that’s gone
into a turn too fast. We’re in the “Oh shit” stage of the wreck. Try as
we might, we spin the wheel but we just keep sliding toward the cliff.
Where are any of the paper currencies without the U.S.? The world is in
very deep shit. I can’t see how anyone is going to make it through this
without getting bloody.
China is in incredibly deep shit. Americans are tapped out.
I expect, (I’ll be writing about this soon), some kind of wildcard event
in 2009 that will cause the elite to move to the next phase. What I mean
is, fewer national currencies. Some drastic emergency measures.
Something radically different to deal with the deepening crisis.
When I say wildcard, it means: I HAVE NO IDEA WHAT IS GOING TO HAPPEN. No idea. I’ve reached a point where it’s incredibly difficult for me to forecast with much accuracy because the tools and assumptions I’ve been relying upon assume a functioning system. Even if that system was based on a bunch of fallacies, everyone agreed that the fallacies were not too problematic and went about their day.
We’re at the point where the Ponzi scheme just can’t perpetuate itself forward anymore because the endemic fallacies are blowing up in our faces.
Via: Financial Times:
A German sovereign bond auction failed on Wednesday as investors shunned one of the most liquid and safe assets in the world in a warning for governments seeking to raise record amounts of debt to stimulate slowing economies.
The fate of the first eurozone bond auction of 2009 signals trouble ahead as governments around the world hope to issue an estimated $3,000bn in debt this year, three times more than in 2008.
The 10-year bonds failed to attract enough bids to reach the €6bn the German government wanted. Bids of €5.24bn, a cover of only 87 per cent, amounted to the second worst auction on record in terms of demand.
Such developments were rare before the credit crisis. Before the seven German bond auctions that failed last year, the last German bond auction to fail was in July 2000 after the dotcom crash.
Analysts said the vast amount of supply is deterring investors and a growing number of countries, including those with deep and mature bond markets, such as Germany, the UK and Italy, are struggling to attract buyers.
The Netherlands has seen bond auctions fail, the UK and Italy have been forced to offer investors higher yields to meet their auction targets, while Spain and Belgium have cancelled offerings because of a lack of demand.
The German finance agency admitted that investor appetite for government debt had waned, although insisted the auction was “not a disappointment”.
Meyrick Chapman, a UBS fixed-income strategist, said when a German bond auction failed it “does suggest there may be trouble ahead for other governments wanting to raise money in the debt markets. Before the financial crisis, German bond auctions just did not fail.”
However, analysts stress the heavy supply is being offset by fears of deflation and recession, which are typically supportive to government bonds and have depressed yields, which have an inverse relationship with price, to historical lows.
The UK on Wednesday successfully sold £2bn in gilts due to mature in 2038. But Robert Stheeman, chief executive of the UK Debt Management Office, has warned that the large supply of debt could deter buyers of gilts. Britain is planning to raise £146.4bn in bonds this financial year – three times more than last year.
Research Credit: JL
Go East, Young Man? Californians Look for the Exit
January 13th, 2009Is it Atlas Shrugged, but with the exodus coming from the middle tiers, rather than the top?
I’m really starting to wonder. So many people are just saying, “F*ck it,” refusing the play along anymore. In general, rich people are out of touch with the reality on the ground, and poor people are trapped. Both classes lack options, the rich because of cognitive dissonance and the poor because of lack of capital. The trend of middle class people, voluntarily (or, involuntarily) taking themselves down several notches, could spell big, BIG trouble for the vampire state. I suppose we’ll know that critical mass occurred when/if a Soviet state like California goes down.
Via: AP:
Mike Reilly spent his lifetime chasing the California dream. This year he’s going to look for it in Colorado.
With a house purchase near Denver in the works, the 38-year-old engineering contractor plans to move his family 1,200 miles away from his home state’s lemon groves, sunshine and beaches. For him, years of rising taxes, dead-end schools, unchecked illegal immigration and clogged traffic have robbed the Golden State of its allure.
Is there something left of the California dream?
“If you are a Hollywood actor,” Reilly says, “but not for us.”
…
Why are so many looking for an exit?
Among other things: California’s unemployment rate hit 8.4 percent in November, the third-highest in the nation, and it is expected to get worse. A record 236,000 foreclosures are projected for 2008, more than the prior nine years combined, according to research firm MDA DataQuick. Personal income was about flat last year.
With state government facing a $41.6 billion budget hole over 18 months, residents are bracing for higher taxes, cuts in education and postponed tax rebates. A multibillion-dollar plan to remake downtown Los Angeles has stalled, and office vacancy rates there and in San Diego and San Jose surpass the 10.2 percent national average.
Median housing prices have nose-dived one-third from a 2006 peak, but many homes are still out of reach for middle-class families. Some small towns are on the brink of bankruptcy. Normally recession-proof Hollywood has been hit by layoffs.
“You see wages go down and the cost of living go up,” Reilly says.
Zimbabwe Introduces $50 Billion Note
January 12th, 2009The old (from July 2008) $100 billion notes used to buy three eggs. The government has since slashed off the zeros and started again. But the zeros came back with a vengeance.
How about using scientific notation?
Via: CNN:
Zimbabwe’s central bank will introduce a $50 billion note — enough to buy just two loaves of bread — as a way of fighting cash shortages amid spiraling inflation.
The country’s acting finance minister, Patrick Chinamasa, made the announcement in a government gazette released Saturday.
Although Chinamasa did not give the date on which the $50 billion and new $20 billion notes would come into circulation, an official at the Reserve Bank of Zimbabwe said the notes would be distributed to all banks by the end of Monday.
Zimbabwe is grappling with hyperinflation now officially estimated at 231 million percent, and its currency is fast losing its value. As of Friday, one U.S. dollar was trading at around ZW$25 billion.
When the government issued a $10 billion note just three weeks ago, it bought 20 loaves of bread. That note now can purchase less than half of one loaf.
Realizing the worthlessness of the currency, the RBZ has allowed most goods and services to be charged in foreign currency. As a result, grocery purchases, government hospital bills, property sales, rent, vegetables and even mobile phone recharge cards are now paid for in foreign currency, as the worthless Zimbabwe dollar virtually ceases to be legal tender.
Once a regional economic model, Zimbabwe is in the throes of an economic crisis, with unemployment running at more than 80 percent and many families unable to afford a square meal. President Robert Mugabe’s critics blame his policies for the economic meltdown, but he says the West is sabotaging his efforts.
In order to attract foreign currency, Zimbabwe’s central bank has, since September, licensed at least 1,000 shops to sell goods in foreign currency. All mobile phone service providers are now licensed to accept foreign exchange for airtime and other services.
John Robertson, an economist in Zimbabwe, said he’s puzzled by the introduction of the $50 billion and $20 billion notes.
“I am not really sure what these notes would be for,” he said. “No one now accepts the local currency. It is a waste of resources to print Zimbabwe dollar notes now. Who accepts a currency that loses value by almost 100 percent daily?”
In August, the RBZ slashed ten zeros from the currency. But the zeroes have bounced back with more vigor.
advertisement
A power-sharing deal between Mugabe and opposition leader Morgan Tsvangirai signed in September, and brokered by former South African leader Thabo Mbeki, raised hopes of halting Zimbabwe’s plunge into economic destruction.
But the pact has stalled over the allocation of key cabinet ministries, with Tsvangirai accusing Mugabe of grabbing all key posts such as defense, home affairs, local government, foreign affairs and finance.
Obama Signals His Reluctance to Look Into Bush Policies
January 12th, 2009The same regime has been getting away with the same types of crimes for nearly 50 years. Obama is complicit in the latest iterations of it. What do the dumbshit “liberals” think he’s going to do, throw himself in jail?
Via: New York Times:
President-elect Barack Obama signaled in an interview broadcast Sunday that he was unlikely to authorize a broad inquiry into Bush administration programs like domestic eavesdropping or the treatment of terrorism suspects.
But Mr. Obama also said prosecutions would proceed if the Justice Department found evidence that laws had been broken.
As a candidate, Mr. Obama broadly condemned some counterterrorism tactics of the Bush administration and its claim that the measures were justified under executive powers. But his administration will face competing demands: pressure from liberals who want wide-ranging criminal investigations, and the need to establish trust among the country’s intelligence agencies. At the Central Intelligence Agency, in particular, many officers flatly oppose any further review and may protest the prospect of a broad inquiry into their past conduct.
In the clearest indication so far of his thinking on the issue, Mr. Obama said on the ABC News program “This Week With George Stephanopoulos” that there should be prosecutions if “somebody has blatantly broken the law” but that his legal team was still evaluating interrogation and detention issues and would examine “past practices.”
Mr. Obama added that he also had “a belief that we need to look forward as opposed to looking backwards.”
Iran Moved Billions via U.S. Banks
January 12th, 2009Via: New York Times:
Iranian banks illegally shifted billions of dollars through American financial institutions in recent years, and authorities suspect some of the money may have been used to finance Iran’s nuclear and missile programs.
Details of the illicit transfers came to light on Friday when New York State and federal authorities announced that a large British bank had agreed to pay $350 million to settle accusations that it had helped the Iranian banks hide the transactions.
The British bank, the Lloyds TSB Group, “stripped” information that would have identified the transfers in order to deceive American financial institutions, which are barred from doing business with Iranian banks, Robert M. Morgenthau, the Manhattan district attorney, said. Lloyds acknowledged its conduct and agreed to turn over detailed records of the transactions.
“They went to great lengths to obliterate any identification,” Mr. Morgenthau said.
The district attorney’s office was still investigating nine major banks that might be engaging in similar conduct, but prosecutors declined to name them. Mr. Morgenthau said, however, that money in one transaction was used to buy a large amount of tungsten, an ingredient for making long-range missiles. He said he suspected that other funds might have been used to finance Iran’s nuclear program.
In the current case, investigators were unsure what the money was used for, said Daniel J. Castleman, the chief assistant district attorney. The stripping made it impossible to determine where the money was going, he said. “We don’t know of any money that has gone to any terrorist organizations, individuals or anything like that,” he said.
Lloyds has agreed to examine all of the transactions it stripped to try to determine where the money was headed. In all, Lloyds hid the source of billions of dollars that passed through the United States, prosecutors said. Lloyds also hid transfers from banks in Sudan, which are also banned from doing business with American institutions.
Half of the $350 million Lloyds has agreed to pay will go to the federal government and the rest to Mr. Morgenthau’s office, which will divide the money between the city and the state.
Mr. Morgenthau said he hoped the money, the largest financial penalty his office has ever collected, would provide a boost to tight city and state budgets.
Although prosecutors did not identify specific individuals at Lloyds responsible for the fraud, Mr. Castleman said, “It was a systemic, wide-ranging scheme.” The training manual given to employees of Lloyds even included a section on how to strip transactions, prosecutors said.
Banks in several nations are banned from doing business with American institutions, but the United States is particularly concerned about Iran, which it says finances terrorists and runs an illicit nuclear weapons program. Iran denies those accusations.
The investigation into Lloyds goes back to 2006. It was conducted jointly by Mr. Morgenthau’s office and the Justice Department, with the assistance of the Treasury and banking regulators.
According to a deferred prosecution agreement, Lloyds handled $300 million of Iranian transfers and $20 million of Sudanese transfers that ended at American banks. Mr. Morgenthau said billions of dollars of transactions went through American banks but ended outside the country.
Several employees in Lloyds’ international payment processing unit in London removed from the bank’s central system orders from certain foreign banks, according to the agreement released Friday by Mr. Morgenthau’s office. Employees struck out identifying information about the originating banks on printed copies of the payment instructions, which someone then re-entered into the payments system. When American banks received the transfers, they seemed to have originated at Lloyds.
Worried that they might be violating American law, senior officials at Lloyds stopped the stripping operation for Iranian banks in 2004, but transfers from Sudan were stripped as recently as 2007.
Under the agreement between Lloyds and Mr. Morgenthau, no employees, officers or the bank will be charged with a crime unless evidence emerges that the bank or its employees and officers knew that specific transfers were sent to or by terrorist groups or “proliferators of weapons of mass destruction.” The agreement lasts for two years.
In recent years, officials in the Treasury have stepped up a campaign to have foreign banks sever links with Iranian banks, which they accuse of providing support for groups like Hezbollah and Hamas, in addition to financing Iran’s own nuclear ambitions.
In November, the Treasury barred American financial institutions from handling certain money transfers for Iranian interests that had been previously allowed, closing what it described at the time as the “the last general entry point for Iranian banks.” Certain exceptions are still allowed for humanitarian aid and remittances.
In December, federal authorities moved to seize the assets of the Assa Corporation, which the Treasury says is a front for Bank Melli, Iran’s largest bank. Assa owns a stake in a Midtown Manhattan office tower.
Mr. Morgenthau’s office had been investigating ties between the Iranian government and Assa and a related entity, the Alavi Foundation, since 2006. Mr. Morgenthau said evidence unearthed in that investigation led his office to inquire about money transfers made through Lloyds.
Research Credit: Lagavulin
Cryptogon Readers Sign Up for Webhosting with Bluehost
January 12th, 2009Thanks to the owners of the following domains for signing up for hosting with BlueHost.
anationoffarmers.com
alpilotx.net
concerted-oblivion.net
ofmarc.us
kenzenware.com
Cryptogon received an astonishing $450 as a result.
U.S. Seeks Ship to Move Unusually Large Amount of Weapons to Israel
January 10th, 2009Colin Powell, October 2008: “There’s going to be a crisis come along on the 21st or 22nd of January that we don’t even know about right now.”
And now, a freakishly large U.S. arms shipment is due to arrive in Israel in two lots, the first on 25 January and the second by the end of January.
Via: Reuters:
The U.S. is seeking to hire a merchant ship to deliver hundreds of tonnes of arms to Israel from Greece later this month, tender documents seen by Reuters show.
The U.S. Navy’s Military Sealift Command (MSC) said the ship was to carry 325 standard 20-foot containers of what is listed as “ammunition” on two separate journeys from the Greek port of Astakos to the Israeli port of Ashdod in mid-to-late January.
A “hazardous material” designation on the manifest mentions explosive substances and detonators, but no other details were given.
“Shipping 3,000-odd tonnes of ammunition in one go is a lot,” one broker said, on condition of anonymity.
“This (kind of request) is pretty rare and we haven’t seen much of it quoted in the market over the years,” he added.
The U.S. Defense Department, contacted by Reuters on Friday in Washington, had no immediate comment.
The MSC transports armour and military supplies for the U.S. armed forces aboard its own fleet, but regularly hires merchant ships if logistics so require.
The request for the ship was made on Dec. 31, with the first leg of the charter to arrive no later than January 25 and the second at the end of the month.
The tender for the vessel follows the hiring of a commercial ship to carry a much larger consignment of ordnance in December from the United States to Israel ahead of air strikes in the Gaza Strip.
A German shipping firm which won that tender confirmed the order when contacted by Reuters but declined to comment further.
CHARTERS “RARE”
Shipping brokers in London who have specialised in moving arms for the British and U.S. military in the past said such ship charters to Israel were rare.
Israel is one of America’s closest allies and both nations regularly sell arms to each other.
A senior military analyst in London who declined to be named said that, because of the timing, the shipments could be “irregular” and linked to the Gaza offensive.
The ship hired by the MSC in December was for a much larger cargo of arms, tender documents showed.
That stipulated a ship to be chartered for 42 days capable of carrying 989 standard 20-foot containers from Sunny Point, North Carolina to Ashdod.
The tender document said the vessel had to be capable of “carrying 5.8 million pounds (2.6 million kg) of net explosive weight”, which specialist brokers said was a very large quantity.
The ship was requested early last month to load on December 15.
In September, the U.S. Congress aproved the sale of 1,000 bunker-buster missiles to Israel. The GPS-guided GBU-39 is said to be one of the most accurate bombs in the world.
The Jerusalem Post, citing defence officials, reported last week that a first shipment of the missiles had arrived in early December and they were used in pentetrating Hamas’s underground rocket launcher sites.
ACTUAL TIMES ONLINE HEADLINE: “PUNISH SAVERS AND MAKE THEM SPEND MONEY”
January 10th, 2009I’ve collected a few quotes to go along with this.
Rather than attempting to bring down The Machine suddenly, in a manner that would, almost certainly, result in the use of strategic nuclear weapons, we should gradually destroy The Machine (and let it destroy itself), while learning the skills necessary to make living in a post collapse reality not only possible, but enjoyable.
How do you gradually destroy The Machine?
Living on as little money as possible, bartering for or buying only what you can’t produce yourself, in my opinion, does a great deal of harm to this system.
—Resistance on the Brink of Oblivion
In America (and wealthier parts of the “West” in general), people don’t have to blow up a natural gas pipeline and shut down a factory or cut enough fiber to crash the NYSE and the NASDAQ market systems for a few minutes, hours or days. Voluntary simplicity, or, living well on very little money, kicks evil people in the nuts and gouges out their eyes. (Pacifists may think of this as sending the enemy Joy and Happiness if they desire.) Doing this in the U.S. has a force multiplier effect because the U.S. is the largest source of the funds that keep the global ponzi scheme running. When people in wealthy countries opt out, the action causes major economic damage to the machine.
…
It’s a matter of hacking The Matrix in an efficient and innovative manner to reduce your monthly expenses to a fraction of previous levels. The extraction/domination system in the U.S. has few effective defenses against people who opt out—to the extent possible—by making smart use of available resources. The system assumes that you’ll stay hooked forever on a lifestyle built around profligate waste and going deep into debt to buy crap that you don’t really want, or need. Indeed, most people are content to go through life this way.
—Mexico Gas Line Explosions Force Major Factories to Close Down
It’s the folks in good shape that the economy has got to watch out for. If consumers who are in good shape decide to cut back on spending in order to reduce their credit card balances, that would take a considerable amount of spending out of the economy. There is some evidence that this has started to happen.
—“We’re Inching Dangerously Close to the Point Where Consumers Run for the Hills”
If a regular insurgency movement reduced the banks and their data centers to piles of smoking rubble and assassinated the executives and members of the boards of directors, that situation would represent a walk in the park compared to what “consumers” are about to do by abandoning their McMansions and stucco boxes.
—Troubled Homeowners: Can’t Pay? Just Walk Away
The American Corporate State is quite literally bankrupt, yet it continues to function do to an increasing flow of foreign capital that serves to finance its unimaginable levels of debt. If an insurgency was able to slow the flow of capital to corporations, by any means, the revenue loss could eventually cause reverberations throughout the economy that would be catastrophic for the American Corporate State and the wider system of institutionalized theft commonly referred to as “global capitalism.”
—Militant Electronic Piracy: Non-Violent Insurgency Tactics Against the American Corporate State
Via: Times:
Assuming interest rates are reduced to about 1 per cent today, it will make little difference to savers if they fall all the way to zero. To all intents and purposes, income from bank accounts will be reduced to nil.
The next logical step, although it may be politically controversial, would be to do the opposite of what the Tories suggest. Instead of reducing taxes on interest payments, the Government could tax all bank deposits and other risk-free savings. This would create a negative risk-free interest rate, encouraging savers either to invest in property, shares and other productive assets – or simply to save less and consume more. In either case, the result would be more consumption and physical investment, less unemployment and faster recovery from the slump.
More: Hard-Hit Families Finally Start Saving, Aggravating Nation’s Economic Woes
Rick and Noreen Capp recently reduced their credit-card debt, opened a savings account and stopped taking their two children to restaurants. Jessica and Alan Muir have started buying children’s clothes at steep markdowns, splitting bulk-food purchases with other families and gathering their firewood instead of buying it for $200 a cord.
As layoffs and store closures grip Boise, these two local families hope their newfound frugality will see them through the economic downturn. But this same thriftiness, embraced by families across the U.S., is also a major reason the downturn may not soon end. Americans, fresh off a decadeslong buying spree, are finally saving more and spending less — just as the economy needs their dollars the most.
Usually, frugality is good for individuals and for the economy. Savings serve as a reservoir of capital that can be used to finance investment, which helps raise a nation’s standard of living. But in a recession, increased saving — or its flip side, decreased spending — can exacerbate the economy’s woes. It’s what economists call the “paradox of thrift.”
U.S. household debt, which has been growing steadily since the Federal Reserve began tracking it in 1952, declined for the first time in the third quarter of 2008. In the same quarter, U.S. consumer spending growth declined for the first time in 17 years.
That has resulted in a rise in the personal saving rate, which the government calculates as the difference between earnings and expenditures. In recent years, as Americans spent more than they earned, the personal saving rate dipped below zero. Economists now expect the rate to rebound to 3% to 5%, or even higher, in 2009, among the sharpest reversals since World War II. Goldman Sachs last week predicted the 2009 saving rate could be as high as 6% to 10%.
As savings increase, economists say, spending is likely to contract further. They expect gross domestic product to decline at an annualized rate of at least 5% in the fourth quarter, the biggest drop in a quarter-century.
“The idea that the American family will quickly spend us out of this recession is a fantasy. It won’t happen,” said Elizabeth Warren, a professor of law at Harvard University who last month was named chair of the Congressional oversight panel tasked with overseeing the distribution of the government’s Troubled Asset Relief Program funds.
In Boise, families like the Capps and Muirs illustrate the paradox. This metropolitan area at the foot of the Rocky Mountains is home to a half-million people and is a base for electronics manufacturers such as computer-chip maker Micron Technology Inc. The area weathered downturns in the early 1990s and 2001, with unemployment rates remaining well below the national average. But now people here are socking away money they once would have spent, contributing in part to failing stores, shuttered restaurants and rising unemployment.
In 2003, the Capps moved to Boise from Swisswater, Pa., after Mr. Capp received an offer to work for Electroglas Inc., a company that makes equipment used in producing semiconductors. Pay for his field-service engineer job started at $65,000, and Boise’s cost of living was lower than Pennsylvania’s. Rick and Noreen and their two children — Noah, now 13 years old, and Ellen, now 16 — were excited to ski in the Rockies instead of the Poconos.
Move to Boise
The Capps sold their Pennsylvania home for $164,000 and bought a slightly larger, 2,200-square-foot home on a cul-de-sac in the Boise suburb of Meridian. They financed the $175,000 home with a 30-year mortgage, at a fixed rate of 5.8%.
Their children settled in well: Ellen sings in the school choir at Meridian High School, while Noah went to a local charter school and signed up for the chess club. In 2006, Mrs. Capp, now 45, finished her bachelor’s degree in psychology from Boise State University, and began working part-time for a mental-health clinic, earning about $10,000 a year. Mr. Capp, 44, also took classes at BSU.
Four years ago, the Capps took out a $25,000 line of credit on their home and used it to buy a large sectional couch for their family room and a used Toyota 4Runner, to go along with the family’s 1995 Toyota Corolla. Over the years, they also built up about $11,000 in credit-card debt and $40,000 in student loans.
But given the rising value of their home and of Mr. Capp’s stock options, their debt didn’t seem alarmingly high, they said. As the resale value of their home reached nearly $300,000 in 2006, the family took trips to Disneyland, paid $900 for ski passes and signed Ellen up for fiddle lessons.
That all changed quickly. The housing market in Boise started to turn downward at the end of 2006, followed by the stock market and the economy. Around the end of 2007, Mr. Capp’s employer began laying off some of its field technicians as customers put off servicing their equipment. “It’s just been one thing after another,” says Mrs. Capp.
The Capps started cutting back. In late spring, they began to trim their spending and paid down about half of their $11,000 credit-card debt. This summer, they used more than half of their government stimulus check, about $1,000, to open a savings account with an attractive interest rate of 5%.
“We never go downtown anymore,” says Mrs. Capp. “We’re trying to consume less gas, less electricity, less food. It’s across the board.”
Even the family’s cable-TV subscription didn’t escape the scalpel. “It’s been killing me because I don’t get the Cartoon Network anymore,” says Noah, a shaggy-haired teen. “I’m missing so many new shows.”
Community Impact
The impact of such decisions is visible around Boise. At Home Federal Bancorp, a $725 million bank with 15 area branches, the number of new savings accounts was up by 26% in December from the previous year, said Steve Eyre, the bank’s head of consumer banking. He said the bank is also seeing people save in their checking or money-market accounts. “It’s pretty interesting to see those balances actually increase at a time when there’s higher unemployment,” he said.
Meanwhile, many downtown restaurants have closed this year, including a number of locally owned eateries. Satchell’s — a family restaurant that was the Capps’ favorite — is gone, as are Zutto Japanese Restaurant, the 8th Street Wine Company, Mortimer’s Idaho Cuisine, Gino’s Grill, the MilkyWay and a French place called Andrae’s. Retail store closings have become so pervasive that the sign outside one surviving store, Dick’s Stereo, now proclaims “WE ARE STILL HERE.”
National retailers are pulling out as well. The Boise Towne Square, the region’s primary shopping mall, is losing one of its anchor tenants, a Mervyn’s department store. A furniture store across the street has also gone out of business. A nearby plaza has lost its two main tenants — Linens ‘n’ Things and Circuit City — as both liquidate nationwide.
Unemployment in the Boise area is still below the national average of 6.7%. But the rate has risen swiftly, to 6% in November 2008 from just 2.7% a year earlier. Unemployment is expected to climb to at least 8% by 2010, according to Moody’s Economy.com, about the same rate forecast for the nation as a whole.
By October, Mr. Capp, too, was out of work. His employer, Electroglas, trimmed its North American work force of field technicians from more than a dozen when Mr. Capp started to just four after he and several colleagues lost their positions, he said. Electroglas, based in San Jose, Calif., declined to comment.
With a severance package of about $10,000, the Capps say they paid off their remaining $6,000 in credit-card debt and have been living off the dwindling remainder.
Keeping the Old Car
Frugality has become a family responsibility. Mrs. Capp, a friendly and effervescent woman, nixed replacing her Toyota Corolla, even though it has 253,000 miles on it, a cracked windshield and Hawaiian-print covers over its splitting seats. The Capps have given up on skiing this year. Disposable paper towels have been replaced by washable rags.
Ellen’s college options are also limited. The family hadn’t started saving for college before the downturn and can’t put away enough money now. “We’re really pushing her toward scholarships or anything that can help pay for it,” says Mrs. Capp. They’ve considered having their tall, lanky daughter try modeling, but portfolio shots cost a couple hundred dollars.
Jessica Muir, too, would like to be socking money away for her children’s college educations. But the 31-year-old mother of three says she also can’t afford it now.
Jessica and Alan were high-school sweethearts in Caldwell, a small community near Boise. They married young. Mrs. Muir worked as a dental assistant before the couple’s first child, Gavin, was born five years ago. In 2006, Mrs. Muir gave birth to twins.
The same year, they bought a modest two-story home in Nampa, part of the Boise metropolitan area, with enough room in back for a vegetable garden. Unable to afford a 20% down payment, they took out two mortgages to buy the $144,000 home. Mrs. Muir cashed in her 401(k), using the roughly $3,000 to pay for insulation and a fence. The Muirs figured they’d get their money back when they sold the house for a higher price a few years later.
IRA Hit Hard
It hasn’t worked out that way, with real-estate prices falling along with the rest of their investments. Alan Muir’s government job as an Agriculture Department grape researcher is more secure than most, but his combined 401(k) and individual retirement account is down by about half, to $13,000.
To pare back, Mrs. Muir started “the Moneysavers Club,” an email group of about 30 people. The members alert each other about deals such as $8 winter coats at Old Navy, and they split bulk purchases of sugar and other staples. Mrs. Muir stores food in her garage, including vegetables she’s grown and canned herself. When she saw a great deal on eggs recently she bought 10 dozen, which she cracked into ice-cube trays, froze and transferred to bags for cold storage. “Not many people know eggs freeze,” she said.
She also sells hand-crocheted hats and scarves on Craigslist and at local bazaars, bringing in $85 on a recent weekend. Her husband, meanwhile, charges $20 an hour for guitar lessons on Wednesday nights, and takes trips into the Rockies with friends to cut firewood for the family’s wood-burning stove. The couple also recently split the $600 cost of a yearling calf with Mrs. Muir’s parents, who are raising it on their land in Caldwell. They plan to butcher it and eat the meat.
The cutbacks by the Muirs and others their age mark a particularly profound shift. In the American buying spree of recent years, the most profligate spenders were those under 35. As recently as 2006, for every $100 these Americans earned, they spent about $117. Those aged 35 to 55 had negative saving rates nearly as large. Only the large number of Americans 55 and older, who have always had high double-digit saving rates, kept the overall saving rate above zero, according to data from Moody’s Economy.com and the Federal Reserve.
Several factors are now pushing saving rates upward, including tighter restrictions on credit and home borrowing. Growth in consumer credit slowed to 1.2% at an annual rate in the third quarter, the Fed said, far lower than the 3.9% pace in the prior quarter.
The Muirs and Capps, like many Americans, also reined in holiday spending this year. Mrs. Muir started her shopping in July to snatch up bargains.
Mr. Capp didn’t want to spend any money at all on family gifts this year. His wife persuaded him that they could spare a few hundred dollars.
The Capps ended up spending about $370 in all, down from about $350 a person in previous years. Rather than spending Christmas day opening one gift an hour — a Capp tradition — they invited neighbors over to play the Nintendo Wii video game that was a Christmas gift for the whole family.
This year, Mrs. Capp and her husband are resolved not to touch the $2,600 they have in savings, and to augment as soon as possible. “You look around, you see the closing stores, and you know someone needs to spend,” Mr. Capp said. “Just not us.”